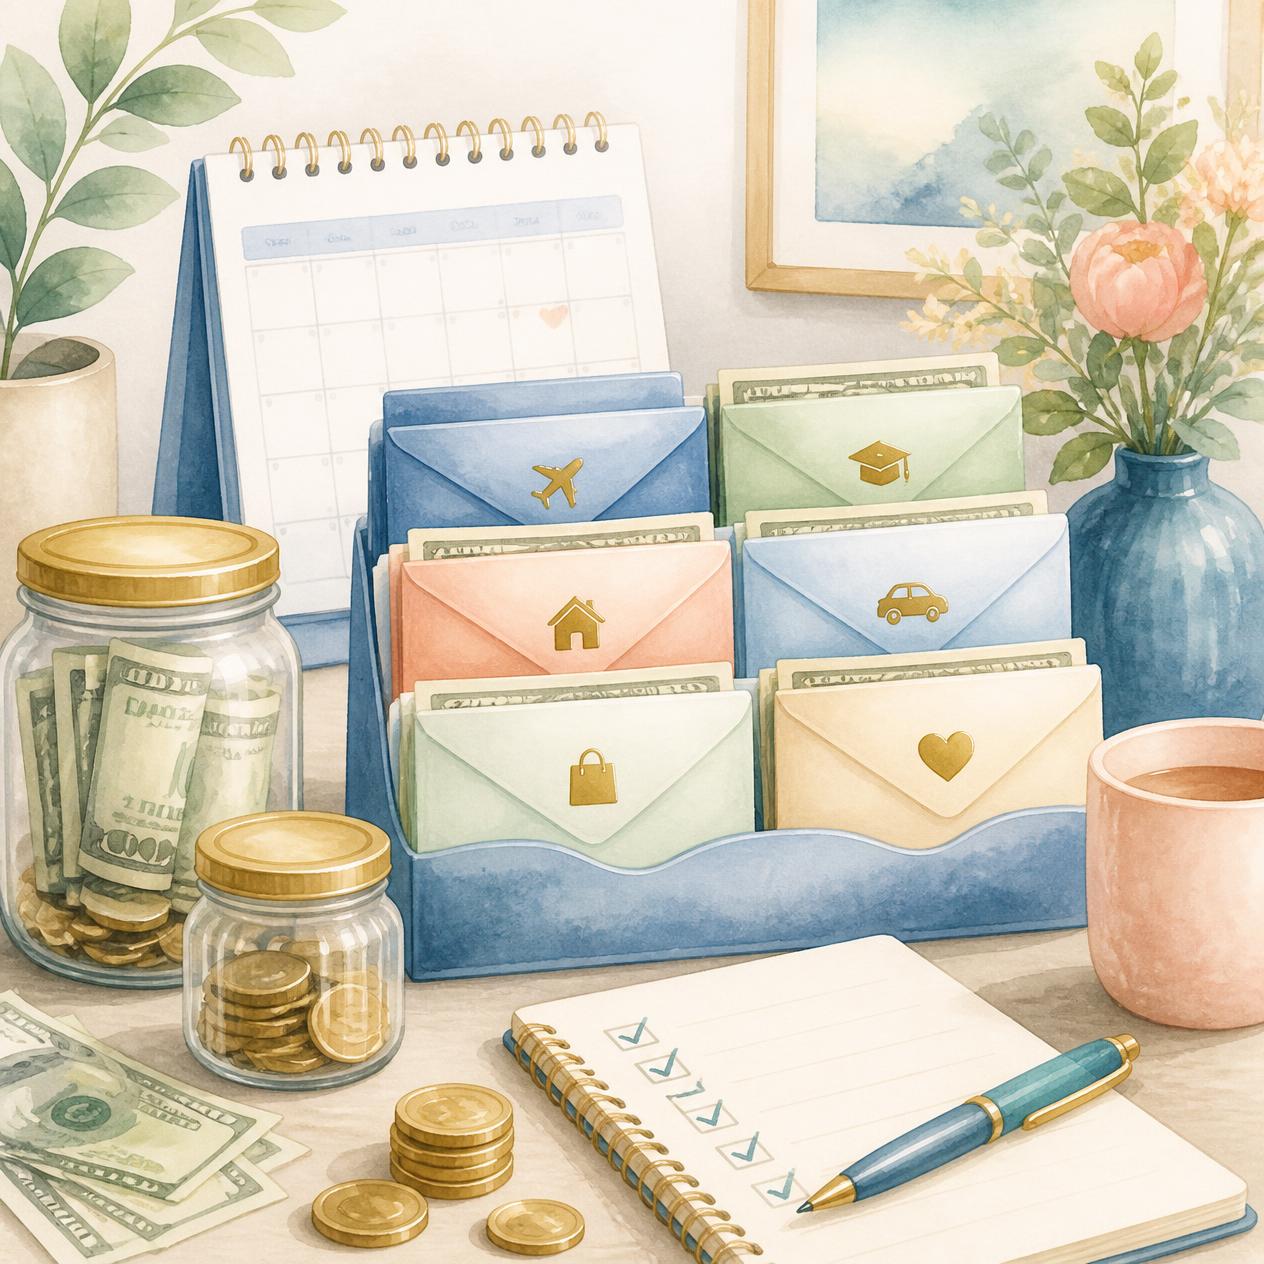
Sinking Funds Explained: The Budgeting Trick That Ends “Where Did My Money Go?”
Let me guess. You sit down, you make a budget, you feel good about it. Then Christmas shows up. Or the car needs new tires. Or your car insurance hits in one big annual lump. And suddenly the whole thing falls apart and you’re back to swiping the credit card and wondering where it all went.
Here’s the truth: your budget isn’t broken. You’re just missing one piece — and it’s called a sinking fund.
A sinking fund is money you set aside a little at a time for an expense you know is coming but that doesn’t happen every month. Instead of getting blindsided by a $600 car repair, you’ve been quietly tucking away $50 a month all year. When the bill comes, the money’s already there. No panic. No debt. No “where did my money go?”
That’s it. That’s the whole trick. And once you start using them, budgeting suddenly feels a whole lot calmer.
Sinking fund vs. emergency fund — what’s the difference?
People mix these up all the time, so let’s clear it up fast.
Your emergency fund is for the stuff you can’t predict — a job loss, a medical bill, the surprise that knocks you sideways. You hope you never touch it.
A sinking fund is for the stuff you can predict — you just don’t want to pay for it all at once. Holidays. Birthdays. Annual subscriptions. New tires. Vet bills. That wedding you’ve been invited to. These aren’t emergencies. They’re life, and life is completely plannable when you look at it head-on.
Think of it this way: an emergency fund is your safety net. Sinking funds are your game plan.
The expenses that deserve a sinking fund
Grab a notebook or open your notes app, because this is where it gets real. Look back over the last year and write down every expense that wasn’t a normal monthly bill. The ones that made you wince. Common ones people forget:
- Christmas and holiday gifts
- Birthdays (yours, kids’, partner, parents)
- Car maintenance, registration, and repairs
- Annual or semi-annual insurance premiums
- Back-to-school shopping
- Vacations and travel
- Vet bills and pet care
- Home repairs and maintenance
- Annual subscriptions (that “surprise” $120 renewal)
- Medical and dental costs not covered by insurance
Most people are carrying five to ten of these a year and never see them coming. No wonder the budget feels impossible.
How to set up a sinking fund in 4 steps
Okay — here’s how you actually do it. This takes about 20 minutes, and it’s the good kind of 20 minutes that saves you a whole year of stress.
- Name the goal and the total. Pick one expense. Say it’s Christmas, and you want $600 to cover gifts.
- Set the deadline. When do you need the money? If it’s August now and you need it by December, that’s roughly 4 months.
- Divide. $600 ÷ 4 months = $150 a month. That’s your sinking fund contribution. If that’s too steep, start earlier next year — the more months you give yourself, the smaller the monthly bite.
- Automate it. Set up an automatic transfer for that amount right after payday so you never even see it. Out of sight, quietly growing, ready when you need it.
Repeat for each expense, and you’ve built yourself a system that absorbs the year’s curveballs before they hit.
Where to actually keep the money
You’ve got a few solid options, and the “right” one is just whatever you’ll actually stick with.
Separate savings accounts. Many banks (especially online ones) let you open multiple free savings accounts and nickname them — “Christmas,” “Car,” “Travel.” This is my favorite because you can see each pot growing.
One savings account, tracked on paper. Keep all the money in a single account and use a simple spreadsheet or notebook to track how much belongs to each category. Less pretty, works just as well.
A budgeting app. If you already use one, most let you create category envelopes or goals that do the math for you.
The method matters way less than the habit. Pick one and go.
Fit it into the budget you already have
Sinking funds aren’t a separate budget — they’re a category inside your budget, treated exactly like a bill. If you’re building a zero-based budget, your sinking fund contributions get a line item just like rent or groceries. Using the 50/30/20 framework? They live in your savings bucket.
And if you’re paid every two weeks, plan your contributions around your pay dates — here’s how to budget a biweekly paycheck so nothing slips through the cracks.
Start small, but start this week
You don’t need to fund every category at once. That’s the fastest way to feel overwhelmed and quit. Pick the one expense that always seems to sneak up and blow your budget — for a lot of people that’s car stuff or Christmas — and start there. One fund. One automatic transfer. This week.
Then, during your weekly money check-in, glance at your fund and watch it grow. There’s something genuinely satisfying about knowing the next “surprise” expense already has money waiting for it.
That feeling — calm instead of panic — is the whole point. That’s what taking ownership of your money actually feels like. And it starts with one small, boring, powerful little fund.
You’ve got this.
Discover more from The Freedom Edit
Subscribe to get the latest posts sent to your email.

2 Comments